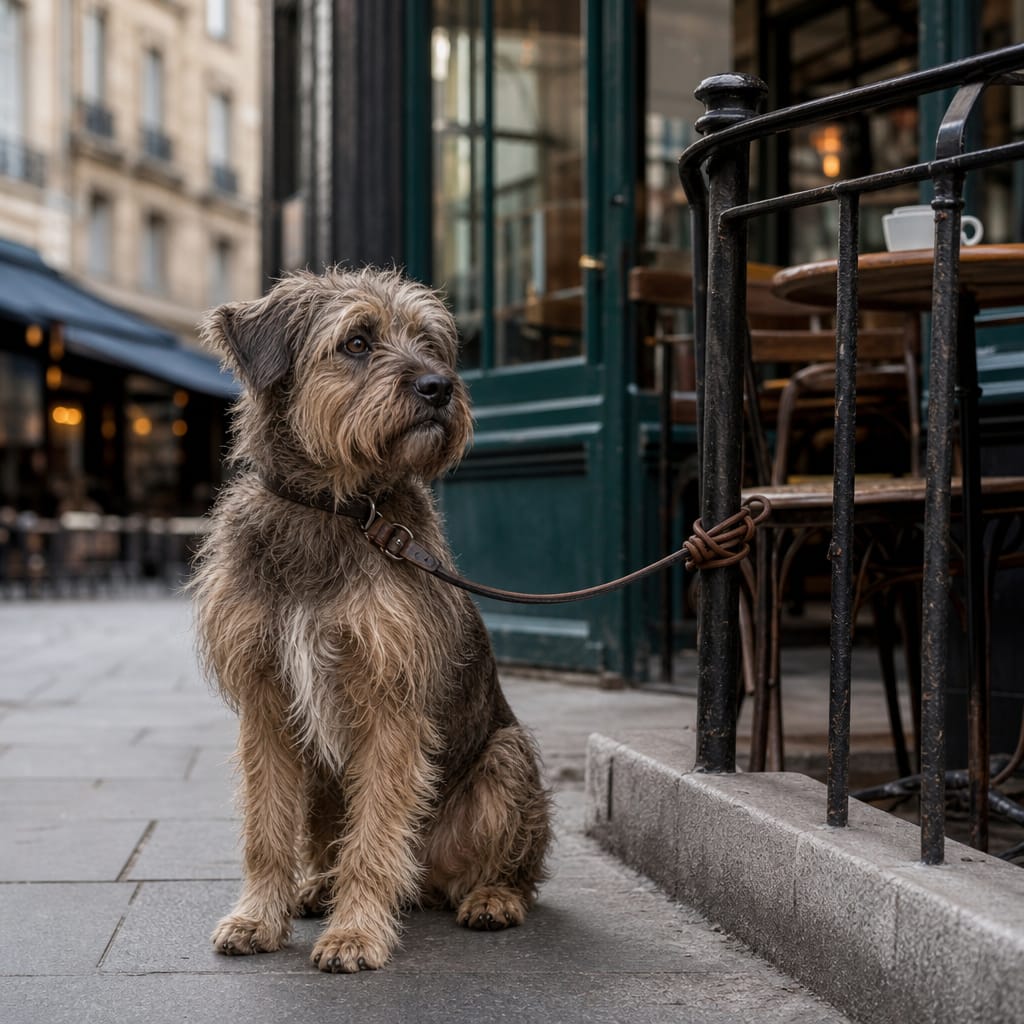
There is a dog tied to a railing outside the coffee shop where you are reading this. Lovely dog. Scruffy ears. Absolutely no legal existence whatsoever. The coffee shop itself, though – that is a different matter entirely. The coffee shop can sign contracts, own a building, sue someone and be sued in return. It can, in some meaningful sense, die. The dog cannot do any of those things, and nobody finds this arrangement strange.
We should find it strange. It is one of the oddest ideas in the history of commerce, and we invented it barely a hundred and seventy years ago.
The Moment the Fiction Was Born
Before the mid-nineteenth century, if you wanted to run a business with other people, you were all personally on the hook. Every debt, every lawsuit, every catastrophic mistake – that was yours to carry. Your house, your furniture, your coat could all be seized to settle the company's debts, because you and the company were the same thing.
Wealthy investors were therefore deeply reluctant to put money into industrial ventures they couldn't personally supervise. This was not ideal at the precise moment Britain needed to build railways, factories, and a great deal of heavy, expensive infrastructure.
The Limited Liability Act of 1855, and the Companies Act that followed it the next year, solved this by doing something philosophically audacious: they declared that a business could be its own legal person. Separate. Distinct. A new kind of entity that had never existed in nature and had to be conjured entirely through paperwork.
What does corporate legal personality actually mean?
The technical term is a "legal person" or sometimes a "corporate person", and it means exactly what it sounds like. This legal person – your limited company – can enter into agreements entirely in its own name. If you start a business as a limited company and it later drowns in debt, the creditors come for the company, not for you personally. You lose what you put in. Your house stays your house.
Which also means the company can outlive you. It can be sold, inherited, restructured. The original founders can die, retire, fall out, emigrate – and the company just keeps going, because its existence was never dependent on any particular human being in the first place. Companies do "die", through formal dissolution or insolvency, but they go through a whole legal process to do it, one that has no biological equivalent.
The Polite Absurdity We All Participate In
Every time you buy something from a shop, sign a lease, or accept a job offer from "the company", you are participating in a shared fiction that two governments in the 1850s cooked up to get venture capital moving. The company on the other end of that transaction is not a person in any way you could point to or shake hands with – and yet it has clearer legal standing than the dog, than your houseplants, than the wind that just blew your receipt down the road.
It works because everyone agrees that it works. Which, on reflection, is more or less how all of the most important things in civilisation operate.
Questions this raises
- When did limited liability become law in Britain?
- Can a company be prosecuted for a crime?
- How does a company legally die?