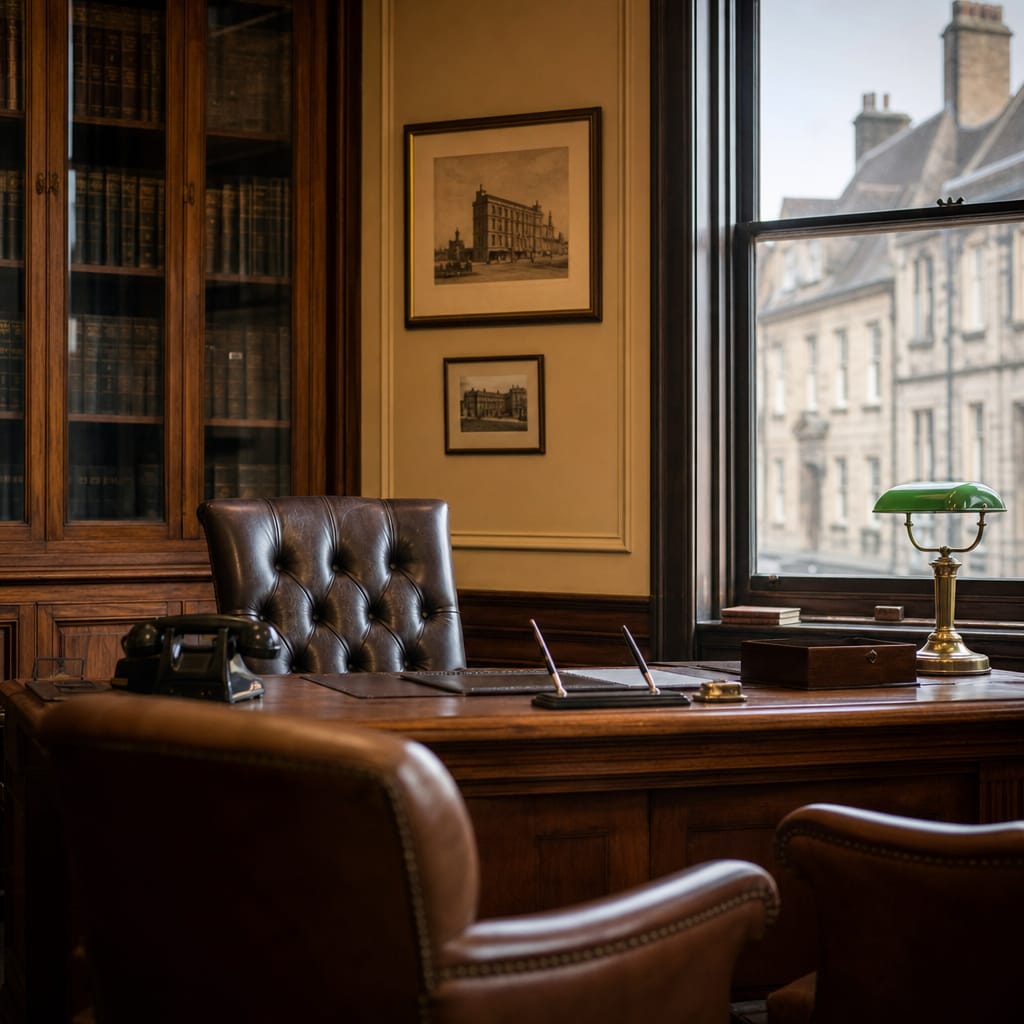
There was a time, not so long ago, when the entire fate of a small British business could turn on whether a particular man in a particular suit liked the look of you. Not your accounts. Not your credit history. You. The way you shook his hand. Whether you'd been introduced through the golf club. What your father did.
The local bank manager in 1970s Britain was not a functionary. He was a figure of genuine, almost baffling power – someone who held actual discretionary authority to approve loans, extend overdrafts, or quietly let a business breathe through a bad quarter, based on his personal read of the situation. He knew the high street. He knew who'd bounced a cheque and who'd quietly made it right. He had lunch with the solicitor and played cricket with the accountant. Somewhere in all that human intelligence was a picture of your business that no spreadsheet could replicate.
The Handshake That Did the Work of a Balance Sheet
This wasn't chaos, exactly. It was a system, just an informal one. The bank manager was the bottleneck – one human being through whom all local credit had to pass – and that meant the whole machinery of small business shaped itself around him. You structured your business to be legible to him. You dressed for the meeting. You wrote deferential letters. You did not ask for too much at once. You built a relationship over years, and that relationship was the collateral.
Risk was understood differently too. A business that had survived a hard winter, visibly, on the same high street for a decade, meant something to a man who walked past it every morning. That kind of evidence doesn't fit a form.
Did credit scoring make lending fairer or just faster?
What replaced him was not another person. It was a score, generated somewhere distant, by criteria the applicant is not shown and cannot address. Credit scoring arrived and standardised everything – the same formula in Bradford and Bristol, no room for context, no one to argue with over a plate of sandwiches. Faster, yes. Fairer, arguably, in some directions. But also completely deaf.
The strange part is what didn't change. You still write formal letters to banks, still dress up for meetings that are essentially data-entry exercises, still speak in careful deferential language to institutions that stopped listening personally somewhere in the mid-1980s. The ghost of the bank manager is still in the room, even though the room is now a portal and the decision is made before you've finished your tea.
This same ghost haunts the language around borrowing more broadly – the terminology of property and finance is full of strange holdovers from an era of personal relationships and local judgements.
The Character Reference Nobody Asks For Anymore
What the bank manager era got right, in its imperfect way, was that it treated a business as a living thing with a history and a person behind it. What replaced it got efficiency right, and got some of the bias out (though not all of it, by any means), but it also made the conversation disappear.
The small business owner who writes a careful covering letter to accompany a loan application in 2025 isn't being naive. They're reaching for something that once genuinely worked – the idea that if you could just explain yourself to someone who understood the place you were operating in, that would count for something. It did, once. Whether it counts for anything now rather depends on which algorithm picks up the file.
Questions this raises
- When did banks take lending decisions away from branch managers?
- How do banks assess small business loans now?
- Can you still meet a business bank manager in person?